


Personal loan for home renovation: Costs and benefits
A Personal Loan for Home Renovation can be used for painting, repair work, or home upgrades. The good news is there are tonnes of lenders willing to offer this loan. Here is all you need to know.

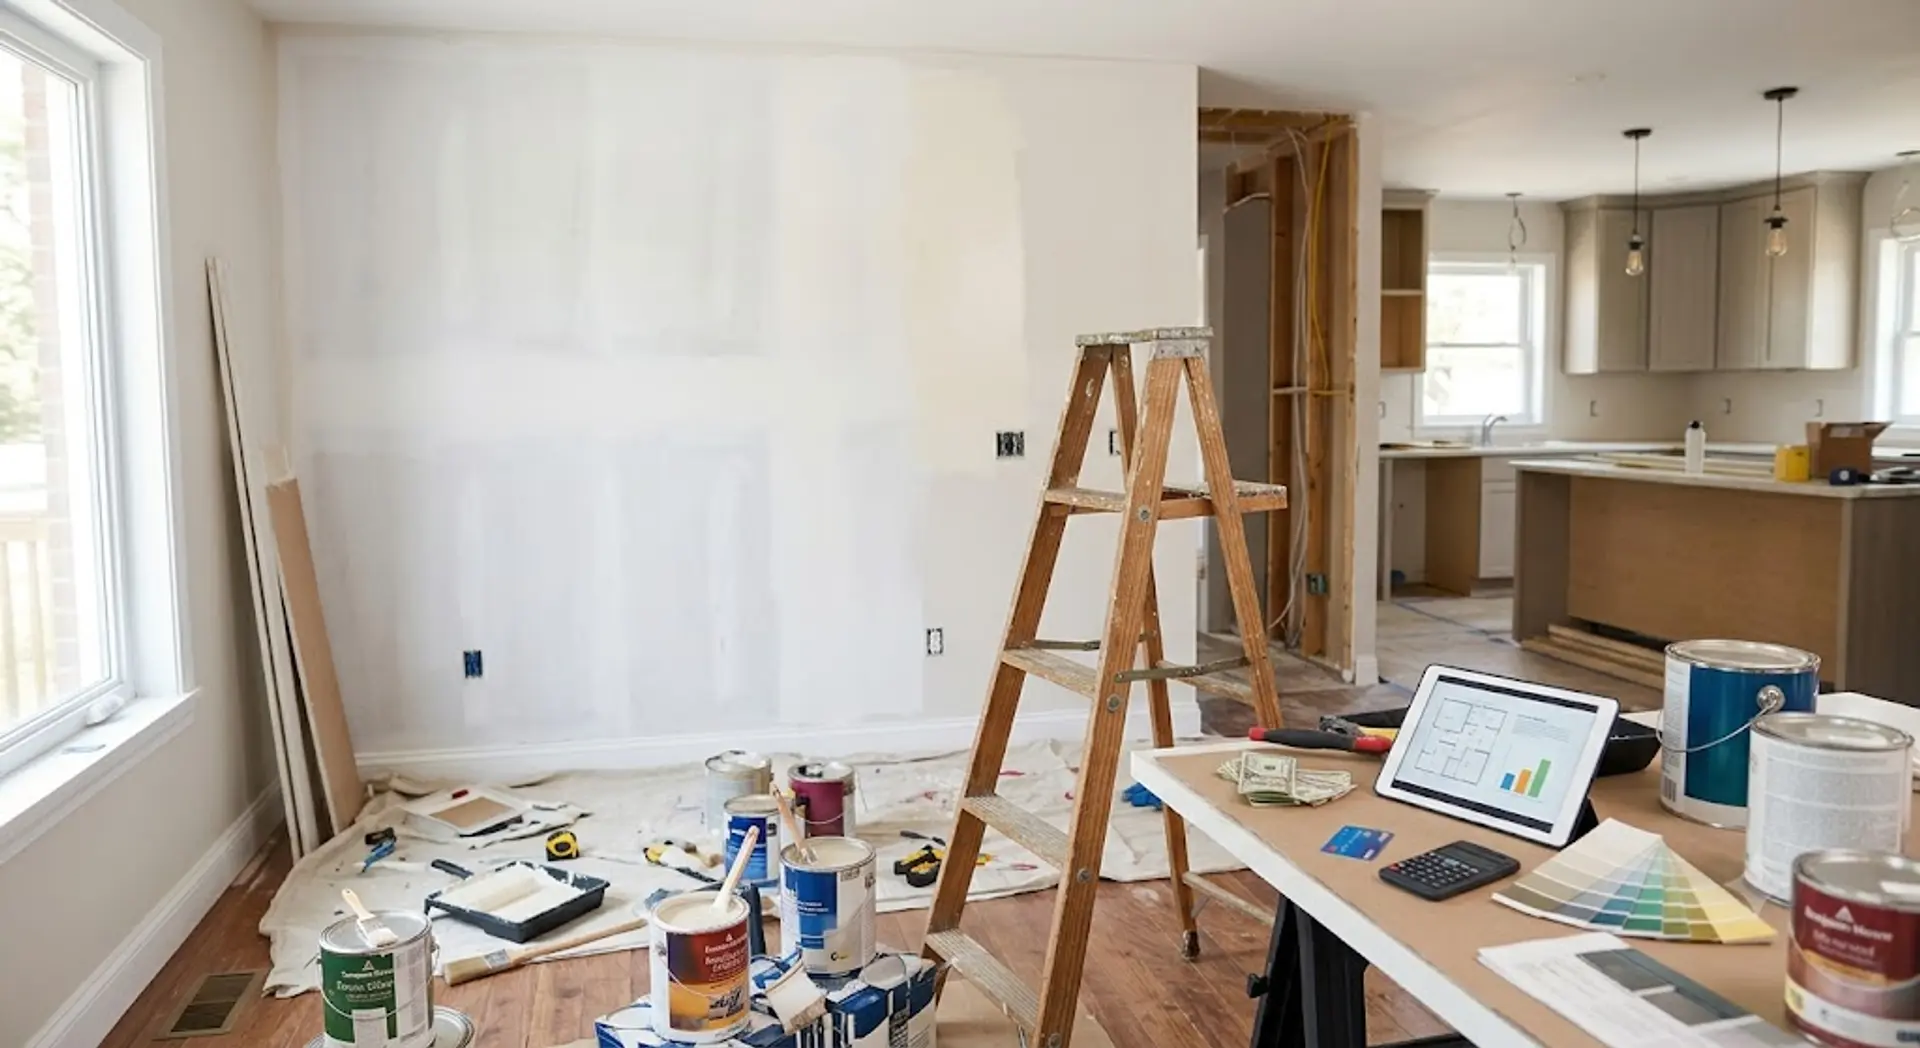
Personal Loans are multi-faceted and can be utilised to pay for various kinds of expenses without end-use restrictions. For instance, you can channel the loan amount to remodel or renovate your home and give it the facelift it needs.
Whether your house needs a lick of paint, repair work, or upgrades, you can do it all using a Personal Loan for Home Renovation. Keep reading to understand the costs and benefits of this loan.
Breaking down the costs
Lenders levy various costs on a Personal Loan for Home Renovation. Some are payable upfront, while others are payable throughout the loan process. Some costs are mandatory, while others are case-based. Here’s what you can expect to pay:
- Loan Processing Fees
Lenders levy an administrative charge to process your loan’s paperwork, known as the processing fee. The fee is typically 0.5-3% of the sanctioned loan amount, usually adjusted or deducted from the loan amount disbursed. But you are expected to repay the actual sanctioned loan amount.
- Taxes and Statutory Charges
Lenders also levy an 18% Goods and Services Tax (GST) on the sanctioned amount, applied to the processing charge and other administrative costs, including stamp duty and loan registration. These charges are not standard across India and vary from state to state.
- Incidental and Third-Party Charges
Your loan may entail incidental and third-party charges such as documentation, statement, and certificate fees, and mortgage guarantee charges, if applicable. These are paid by the lender to third parties for documentation verification services. Lenders typically pass on these costs to borrowers.
- Loan Interest
The interest payable against the loan takes up the biggest chunk of the loan’s cost. It is repaid as part of your Equated Monthly Instalments. A lower interest rate translates to a larger EMI but a shorter tenure, while a higher rate translates to affordable EMIs paid over a longer tenure.
- Prepayment and Foreclosure Charges
Prepayment and foreclosure charges are case-based, levied only if you choose to repay and close off your loan before its stipulated tenure ends. Most lenders levy a fee of 2-5% on partial prepayment or foreclosure. However, these fees are often waived on floating-rate loans.
- Late Payment and EMI Bounce Charges
This is another case-based charge, which only applies to borrowers who default on EMI payments. Lenders typically levy a penal interest rate of up to 18% on overdue EMIs. They also levy an additional cheque/instalment bounce fee if the EMI cheque bounces or the auto-debit of the EMI fails.
- Conversion or Switching Fees
Some lenders allow you to convert your fixed-interest-rate loan to a floating-rate loan, while others may accept your request to lower the interest rate. In such cases, they levy a conversion/switching fee, which is usually 0.5% (capped at Rs 50,000) of the outstanding principal loan amount.
- Hidden Renovation-Linked Costs
Besides the loan charges, your Personal Loan for Home Renovation may entail unpredictable costs that you may not have estimated, such as sudden electrical work, debris removal, waterproofing, temporary living costs, etc. It helps to add a 15% contingency to contractor quotes before borrowing.
Benefits of a Personal Loan for Home Renovation
Let’s now assess the many benefits of a Personal Loan for Home Renovation.
- Collateral-free: A Personal Loan is generally unsecured, meaning you do not need to risk or pledge your property as collateral.
- Quick disbursal: Most lenders disburse Personal Loans directly into your account within 48 hours. This means that you can access this loan faster than a home improvement loan.
- Flexible usage: Since there are no restrictions on using the loan amount, you can use it to pay for new furniture and appliances, interior decoration, wiring, house repairs, etc.
- Customisable tenure: Lenders allow you to choose your preferred repayment tenure, usually lasting from 12-84 months. You can tailor the tenure as per your repayment capacity.
- Fixed EMIs: Lenders provide you with the amortisation table, which provides details of each EMI, making the loan and the monthly outflow of cash predictable and easier to budget.
- Prepayment option: Lenders also permit you to close the loan before its stipulated tenure. If surplus funds arise, you can exercise this option and reduce your loan’s cost.
- No explanation: Unlike specialised renovation loans, you do not need to provide detailed project estimates. The lender simply sanctions the amount you require.
Every few years, your house may need some life infused into it. Without risking it as collateral, you can access the funds you need by applying for a Personal Loan for Home Renovation.
The good news is that there is no dearth of lenders willing to offer this loan. You can choose from banks, NBFCs, and even modern mobile loan apps offering this facility.
(Disclaimer: The views and opinions expressed in this article are those of the author and do not necessarily reflect the views of YourStory.)